Crisis Management: How Insurance Supports Corporate Reputation During Events
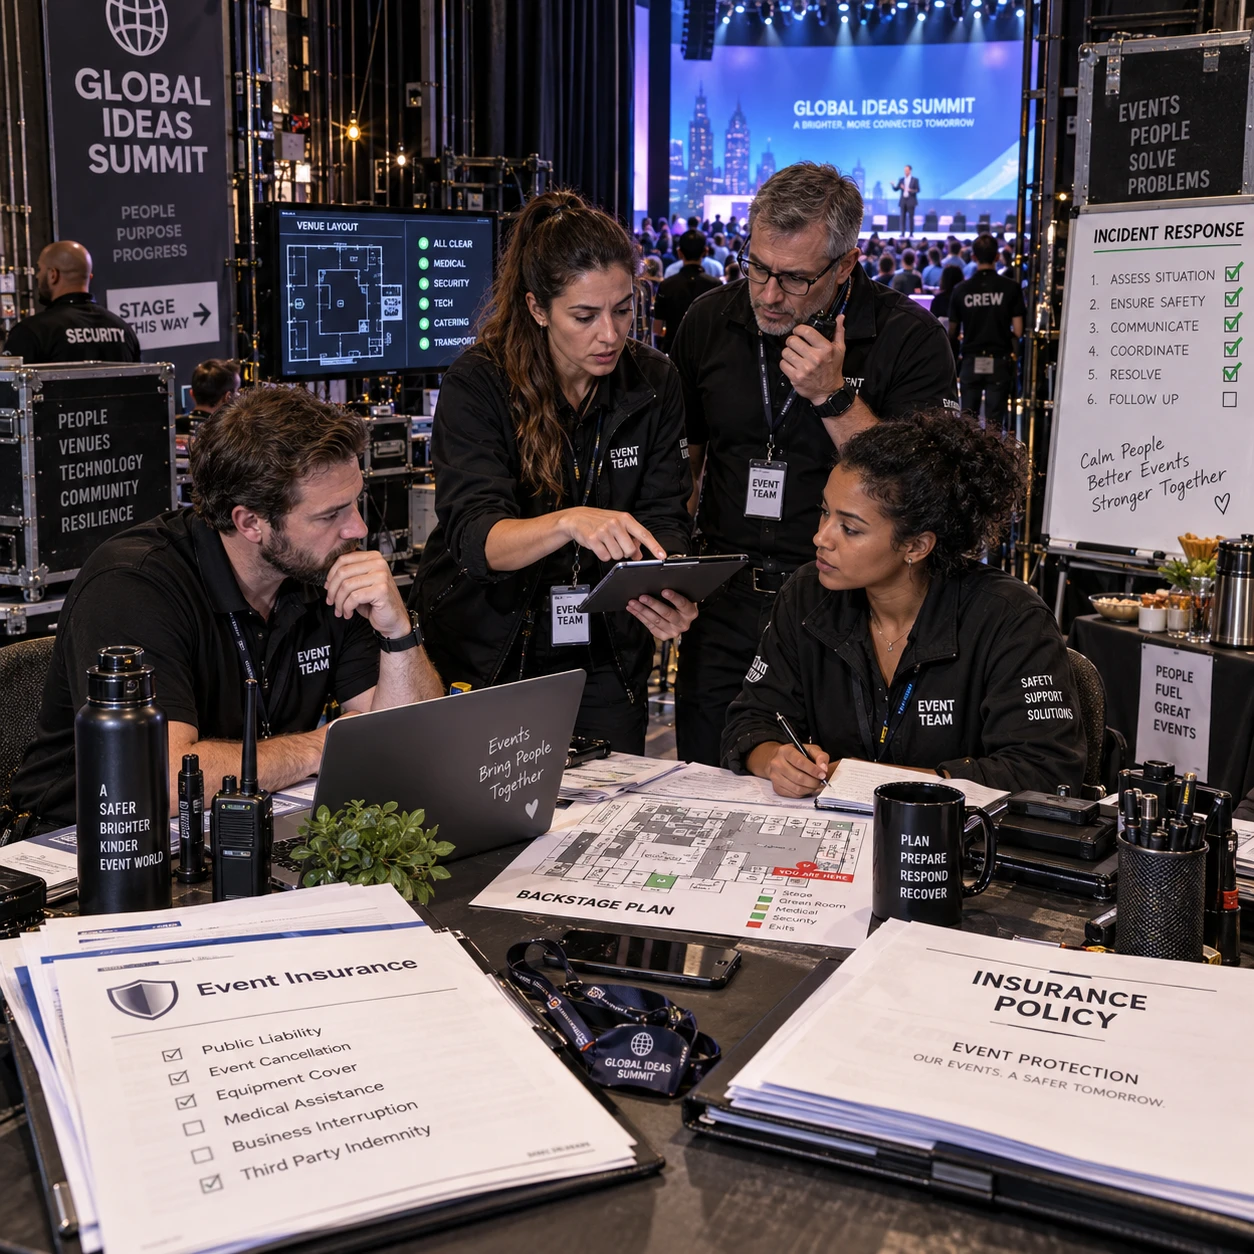
A corporate event can strengthen relationships and build trust, but a cancellation, injury, severe-weather disruption, or technical failure can quickly put that trust under pressure. Event insurance can help fund parts of a response and recovery, giving an organization more room to act responsibly. It cannot guarantee coverage or prevent reputational harm, and it never replaces sound crisis leadership.
The practical goal is to connect risk assessment, policy terms, claims handling, and crisis communications before an event begins. That way, if something goes wrong, decision-makers can focus on people and clear information while understanding how to seek potential insurance support.
Why events create reputational risks
Events create reputational risks because a disruption can affect attendee safety, access, and expectations in public. How an organization responds often shapes stakeholder trust as much as the original incident.
Attendees may share photos and accounts before organizers have confirmed what happened. Employees, sponsors, vendors, customers, and media can then form impressions based on incomplete information. A delayed statement or confusing instructions can make a manageable problem appear careless; a timely, factual response can help demonstrate that organizers take their responsibilities seriously.
Common event pressures include:
- Safety incidents: An attendee or worker is injured, or a crowd-control issue requires an urgent response.
- Operational disruption: Severe weather, a power outage, transport problems, or a venue issue affects the schedule.
- Service failures: A supplier, registration system, catering team, or audiovisual provider cannot deliver as planned.
- Communication gaps: Attendees receive conflicting updates or do not know where to get help.
Risk assessment should consider both the chance of an incident and its potential impact on people, event operations, and public confidence. Insurance can address certain financial losses, subject to the policy. Reputation, however, also depends on choices made in real time: protecting people, sharing accurate updates, and treating affected stakeholders fairly.
Where insurance fits into crisis management
Insurance fits into crisis management by potentially funding covered costs or losses, subject to policy terms, exclusions, limits, and the facts of the incident. It supports the response; it does not direct it.
A crisis team still needs clear leadership. Someone must make decisions about attendee safety, event suspension, emergency services, staff instructions, and public statements. The insurance broker and insurer can help clarify notification requirements and the claims process, but organizations should not wait for a coverage decision before taking necessary safety measures.
Think of the relationship as a three-part operating plan:
- Lead: The organization’s designated crisis lead makes operational and safety decisions.
- Inform: Communications staff provide accurate, coordinated updates to attendees and other stakeholders.
- Document and notify: The designated insurance contact records relevant facts and follows the policy’s reporting process.
These roles may overlap in a small organization, but assigning them in advance reduces confusion. Insurance may help with eligible costs, while crisis communications protect the quality and consistency of information. A claims discussion should not dictate what the organization says publicly; messages should remain truthful and appropriate to the situation.
Event-related coverages to consider
Event-related insurance may address cancellation, liability, or other specified losses, but what is covered depends on the policy and circumstances. Review the wording rather than relying on a coverage label alone.
Event cancellation coverage may apply when an insured event cannot proceed or must be postponed for a covered reason. Policies can define covered causes, waiting periods, deductibles, and recoverable expenses differently. A forecast of bad weather, for example, may not trigger coverage if the policy requires a particular threshold or an actual inability to hold the event.
Public liability coverage may respond to certain claims alleging injury or property damage connected with the event. Limits, exclusions, insured parties, and contractual obligations matter. Organizers should check whether the policy addresses the event’s activities, venue arrangements, contractors, and any required certificates of insurance.
Business interruption coverage may apply to specified interruptions and resulting losses, but it is not automatically included in event insurance or triggered by every disruption. Ask what event, property damage, or other conditions must occur for cover to apply.
Depending on the program, organizations may also need to review equipment, property, workers’ compensation, cyber, or vendor coverage. These are not interchangeable. An insurance broker can help map exposures to policies and identify potential gaps, while the insurer’s issued wording remains central to determining coverage.
Preparing coverage before the event
Prepare event coverage by assessing likely exposures, checking policy wording, coordinating with vendors, and assigning clear responsibilities before opening day. Early review gives the organization time to address gaps or clarify requirements.
Use a practical coverage check
- Map the event: Record the venue, dates, attendance, activities, equipment, suppliers, and travel or weather dependencies.
- Rank the risks: Consider what could harm people, stop the event, damage property, or disrupt a key service. Include low-probability events if their consequences would be severe.
- Compare risks with policies: Check insured entities, covered causes, exclusions, limits, deductibles, notice deadlines, and any conditions that require advance action.
- Coordinate contracts: Confirm who insures which risks, what certificates are required, and whether indemnity or cancellation clauses create responsibilities.
- Assign contacts: Name the crisis lead, communications spokesperson, event operations contact, and person responsible for insurer or broker notification.
Ask the broker specific questions: Does the policy cover postponement as well as cancellation? Are supplier failures treated differently from venue failures? What records should be kept, and how quickly must an incident be reported? Get clarifications in writing when possible, and do not assume that a vendor’s insurance covers the organizer’s own obligations.
There is a trade-off in buying broader limits or additional coverage: it may offer more financial protection, but it adds cost and still cannot remove every exclusion or reputational consequence. Match coverage to the event’s actual exposure and the organization’s ability to absorb a loss.
Responding when a crisis occurs
When an event crisis occurs, protect people first, activate the response plan, notify the appropriate insurance contact promptly, and preserve accurate records. Follow the policy’s reporting requirements, since late or incomplete notice can complicate a claim.
Start with immediate safety and operational decisions. Contact emergency services when needed, provide clear instructions to attendees, and pause or evacuate activities if the situation calls for it. Do not delay a necessary response while waiting for an insurer’s approval. Once the immediate risk is addressed, use this sequence:
- Record the facts: Note times, decisions, weather or system conditions, witness details, supplier communications, and actions taken. Keep original documents and relevant photographs where appropriate.
- Notify through the right channel: Contact the broker or insurer according to the policy. Share known facts without guessing about causes, liability, or coverage.
- Track costs and losses: Separate invoices, refunds, extra expenses, damaged property records, and other potential claim materials. Ask before disposing of damaged items or making non-urgent repairs if the policy requires inspection.
- Coordinate communications: Give attendees and stakeholders timely updates about what is known, what remains uncertain, and where to get help.
Keep communications human and specific. For example, an organizer facing a venue power failure can state that the program is paused, explain where attendees should go, and promise a time for the next update. It should avoid speculation about fault or assurances that expenses will be reimbursed before the insurer has assessed the claim.
The claims process may require follow-up records, cooperation, and review of policy conditions. Keep one incident log and a central record of insurer correspondence so operational teams and claims contacts work from consistent information.
What insurance can—and cannot—do for reputation
Insurance can help pay certain covered losses, which may give an organization more capacity to manage disruption and meet obligations. It cannot erase public criticism, restore confidence automatically, or guarantee compensation for reputational damage.
Some policies may address specific crisis-response expenses, but that depends on the wording and the triggering conditions. A standalone loss of reputation is not automatically insured simply because an event attracted negative attention. Even when a claim is accepted, payment does not resolve questions from attendees, employees, sponsors, or customers about how the organization behaved.
Reputation recovery relies on actions insurance cannot perform: acknowledging verified facts, explaining decisions, supporting affected people, correcting errors, and following through on commitments. Use insurance as one resource in that work, not as a substitute for accountability. A strong response connects financial readiness with visible care and reliable communication.
Frequently asked questions
Does event insurance cover reputational damage?
Usually, organizations should not assume that event insurance covers reputational damage by itself. Some policies may cover defined crisis-response costs, but eligibility depends on specific wording, exclusions, and circumstances. Ask the broker to identify the relevant clause and limits.
When should an organization notify its insurer after an incident?
Notify the insurer or broker as soon as the policy requires and as soon as practicable after discovering a potentially relevant incident. Check the notice conditions in advance; reporting promptly does not mean admitting fault or confirming that a claim is covered.
Can insurance cover event cancellation or interruption?
It can, when the organization has an applicable policy and the circumstances meet its terms. Covered causes, deductibles, limits, exclusions, and documentation requirements vary, so review the wording before the event and confirm how postponement differs from cancellation.
How can organizations align insurance with a crisis communications plan?
Name an insurance contact and a communications lead, include notification steps in the event response plan, and agree how verified information will be shared. Keep public updates factual and prompt, while routing claim questions through the broker or insurer. This coordination supports both an orderly claims process and consistent communication.