Understanding Cancellation Insurance for Corporate Campaigns
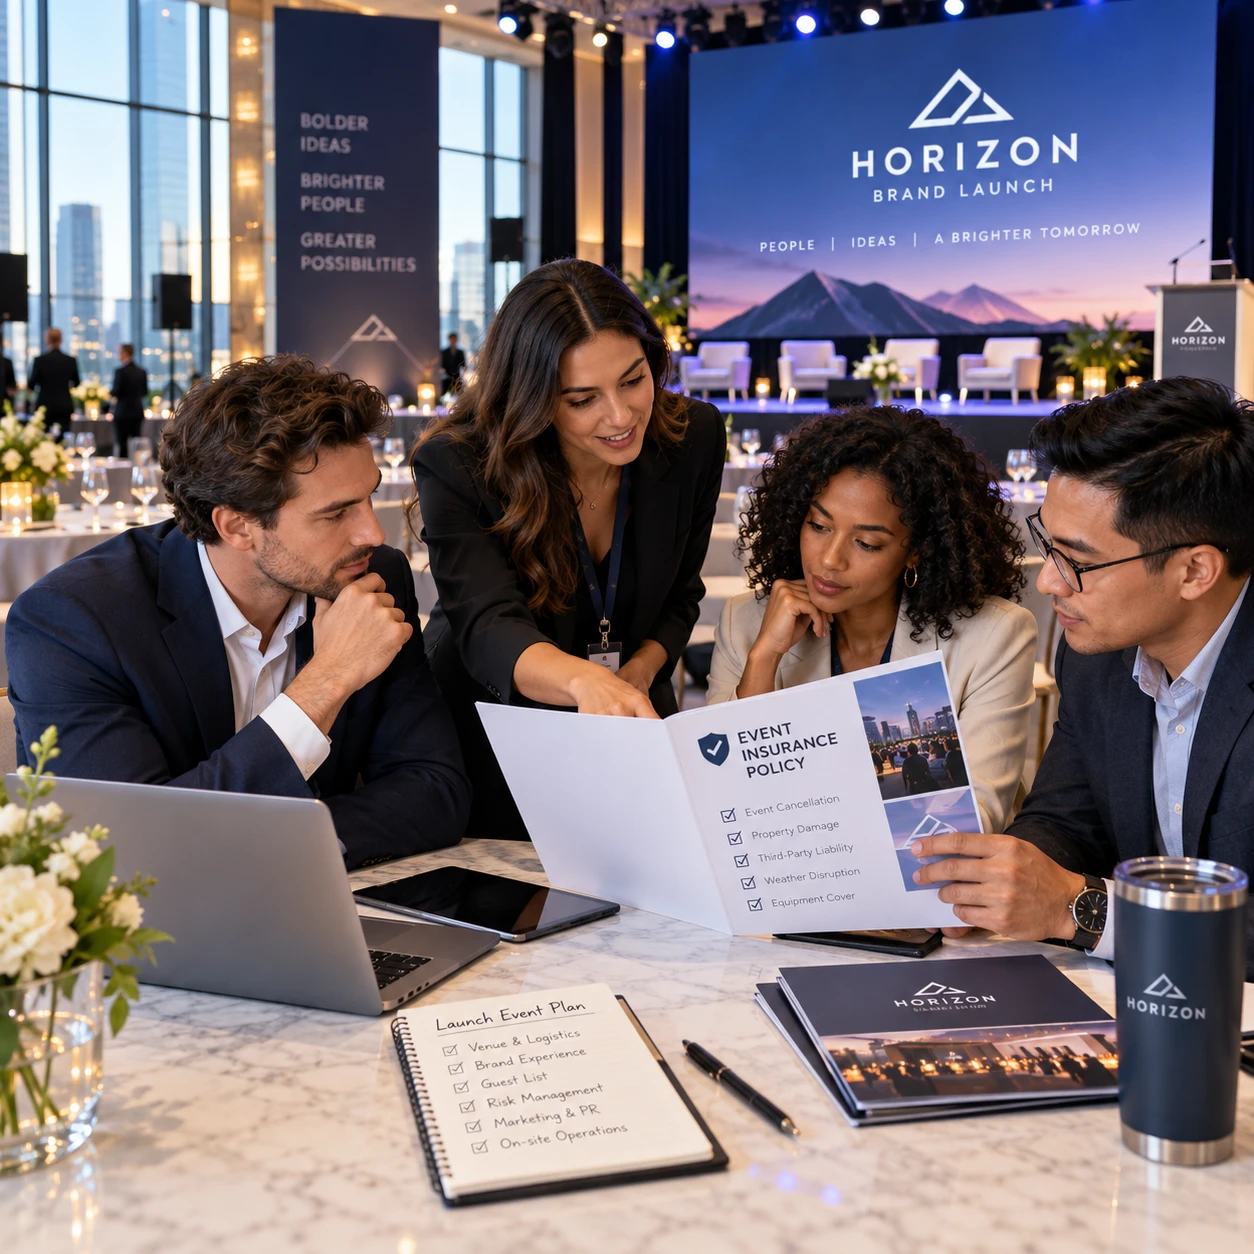
A corporate campaign can involve months of planning and substantial commitments to venues, production teams, suppliers, and media. If an unexpected event forces a launch, conference, or promotional activation to stop, some costs may be difficult to recover. Cancellation insurance can help protect against specified financial losses, but only when the cause and expenses meet the policy’s terms.
Understanding the wording before you buy is essential. Coverage varies by insurer, and a policy may treat cancellation, postponement, and disruption differently. Use the points below to assess what protection a corporate campaign may need and what to verify with an insurer or qualified adviser.
What cancellation insurance means for corporate campaigns
Cancellation insurance can reimburse eligible, non-recoverable campaign expenses when an insured event prevents a covered corporate event from going ahead. The policy defines the insured event, eligible costs, limits, and conditions; it does not automatically cover every cancellation or loss.
For corporate campaigns, the insured event might be a product launch, press event, brand activation, conference, or another scheduled activity named in the policy. Depending on the wording, a covered cancellation may occur when a specified cause makes it impossible or impractical to hold the event. The insured organization generally needs to show that it incurred a financial loss and took reasonable steps to limit it.
Think of the policy as a contract-specific safety net, not a guarantee that the campaign budget will be restored. The central question is whether the cause of the cancellation and each claimed expense fit the policy wording. A campaign can lose commercial value without meeting the policy’s definition of an insured loss.
Which campaign costs may be insured?
Cancellation insurance may cover certain campaign costs that the policy identifies as insured expenses and that the organization cannot recover elsewhere. A cost being part of the campaign budget does not, by itself, make it eligible.
Depending on the policy and event details, expense categories to review may include:
- Venue costs: deposits, rental fees, or other contracted charges that remain payable after cancellation.
- Production expenses: staging, lighting, sound, set construction, or technical services already commissioned.
- Supplier commitments: fees for catering, equipment, security, transportation, or specialist contractors.
- Campaign materials: certain printed or branded items made specifically for the event, if the policy allows them.
- Additional costs: reasonable expenses incurred to reduce a covered loss or carry out an approved alternative, where the wording permits.
Check whether costs are covered on a gross basis or only after refunds, credits, or other recoveries. A refundable venue deposit, for example, may not represent a final loss. Likewise, a supplier credit might reduce the claim even if it cannot be used for the rescheduled campaign. Ask the insurer how recoveries, taxes, and costs shared across several campaign activities are treated.
Events and circumstances that can trigger a claim
A claim may be possible when a specified insured circumstance causes the corporate campaign to be cancelled, postponed, or disrupted. The actual triggers depend on the policy, so confirm the exact wording rather than relying on a general list of possible events.
Policies may address circumstances such as venue damage, certain emergencies affecting access, or the unavailability of a key person, but these are not universal guarantees of coverage. A cause may be covered only if it meets specific definitions and conditions. For example, a venue problem might qualify under one policy but fail another policy’s requirements about the location, timing, or nature of the damage.
Cancellation usually means the event will not proceed as planned. Postponement means it moves to a later date, while disruption can describe an event that goes ahead in a reduced or altered form. These distinctions matter: a policy may cover one outcome, impose a separate sub-limit for another, or require insurer approval before extra costs are incurred. Read the definitions and ask how the policy handles a campaign that proceeds with fewer attendees, a changed venue, or a delayed launch.
Exclusions, limits, and policy conditions to check
Exclusions, coverage limits, and policy conditions determine when cancellation insurance responds and how much it may pay. Review these terms alongside the covered events and insured expenses before relying on the policy.
Common areas to examine include:
- Exclusions: causes or losses the policy does not cover, which may include certain known circumstances, voluntary decisions, or losses outside the stated insured events. The wording controls.
- Coverage limits and sub-limits: maximum amounts payable overall or for specific costs, people, locations, or event outcomes.
- Deductibles or excesses: amounts the insured must bear before any payment may apply.
- Notice deadlines: requirements to report a possible loss or cancellation within a stated period.
- Mitigation duties: expectations to seek refunds, negotiate credits, or otherwise reduce the loss.
- Approval requirements: restrictions on changing the event or incurring additional costs without the insurer’s consent.
Pay close attention to known circumstances and timing. Buying cover after a problem is already foreseeable may not protect against that problem, and a policy can have specific rules about when coverage begins. These details vary, so obtain the complete policy wording and ask the insurer or a qualified adviser to explain unclear terms. A short summary or sales description may not include every condition.
How to assess coverage for a corporate campaign
To assess cancellation insurance, estimate the campaign’s non-recoverable costs, compare them with policy limits, and check whether realistic disruption scenarios fit the covered events. Base the decision on contracts and policy wording, not the headline limit alone.
A practical review can follow four steps:
- Map the exposure. List committed costs by supplier, due date, refundability, and cancellation penalty. Separate confirmed expenses from estimates.
- Check recovery options. Identify deposits that can be returned, supplier credits, rescheduling rights, and other insurance that may respond. Only the remaining potential loss may be relevant to a claim.
- Match scenarios to wording. Consider plausible threats to this particular campaign, such as a venue becoming unusable or a key participant being unavailable. Ask the insurer whether each scenario meets the policy definition.
- Test limits and conditions. Confirm the policy limit is appropriate for the potential insured loss, then check sub-limits, deductibles, notice requirements, and any approval rules.
Timing matters. Campaign costs can rise as the date approaches, while supplier cancellation terms may become less flexible. Get quotes and review cover before making major commitments where possible. Choosing a higher limit may offer more headroom, but it can cost more and still leave excluded causes or expenses uninsured.
Keep supplier contracts aligned with the insurance review. A contract that allows a credit or rescheduling may reduce the amount at risk; a strict non-refundable commitment may increase it. Do not assume the policy will match every contractual loss. Ask how the insurer treats each major expense category and document the answer.
What to do if a campaign is cancelled
If a corporate campaign is cancelled or materially disrupted, notify the insurer promptly and follow the policy’s claim instructions. Preserve records, limit avoidable costs where reasonable, and do not assume reimbursement until the insurer assesses the claim.
Start by recording what happened, when the organization learned of it, and how the event affected the campaign. Contact the insurer or broker using the required notification method, even if the final loss is not yet known. Ask whether the insurer needs to approve rescheduling, replacement suppliers, or other steps before the organization commits to them.
Claim documentation may include:
- The policy schedule and relevant policy wording.
- Venue, supplier, production, and talent contracts, including cancellation terms.
- Invoices, receipts, proof of payment, and a breakdown of claimed insured expenses.
- Written cancellation notices, supplier responses, refund offers, and credits.
- Records explaining the cause of cancellation and its effect on the event.
- Evidence of reasonable steps taken to reduce costs or recover amounts.
Keep a clear timeline and retain original records. The insurer may request further evidence or clarification, and requirements differ between policies. Present the claim accurately, distinguish paid costs from future commitments, and disclose refunds or credits received. These steps support a more complete assessment; they do not guarantee that a claim will be accepted.
Frequently asked questions
Does cancellation insurance cover postponement as well as cancellation?
It may, but postponement is not automatically covered just because cancellation is. Check whether the policy defines postponement as an insured outcome, what costs it recognizes, and whether advance approval is required.
Which expenses can a corporate campaign policy cover?
Depending on the wording, eligible expenses may include non-recoverable venue, production, supplier, or campaign-material costs. Confirm each category, applicable sub-limits, and how refunds or credits affect the amount claimed.
Are all reasons for cancelling a campaign insured?
No. Cover applies only to reasons that meet the policy’s insured-event definitions and are not excluded. Check the wording for the specific circumstance and ask the insurer about any ambiguity.
What documents may be needed for a claim?
Insurers may request contracts, invoices, proof of payment, cancellation notices, supplier refund or credit records, and evidence of the cause and resulting loss. Follow the policy’s notification and documentation requirements.